
Headlines about the Social Security Trust Fund “running out of money” can understandably unsettle retirees and high‑earners alike. But the situation is more nuanced than the sound bites suggest. Bernstein Private Wealth Management explores what projected depletion actually means, which reforms are most likely, and how affluent families should incorporate Social Security into broader retirement and wealth transfer planning.
Every year, the Social Security Trustees estimate how long trust‑fund assets can cover scheduled benefits. Current projections place Old-Age and Survivors Insurance (OASI) depletion in 2033—assuming Congress makes no changes.
What depletion doesn’t mean:
What depletion does mean:
Yet affluent investors—who are accustomed to probability‑based planning rather than headline‑driven reactions—may want to ask a different question: How does uncertainty about Social Security reform influence their retirement strategy?
Congress has adjusted Social Security many times, including the major bipartisan overhaul in 1983 that pushed the original exhaustion date back by five decades. Today’s reform menu is well modeled and familiar:
None are politically painless, but all are politically available. Historically, Congress has preferred reforms that preserve benefits for lower‑income households while shifting more of the fiscal adjustment to higher‑income earners.
1. Don’t Dismiss Social Security as Irrelevant or “Ancillary”
Even for affluent retirees, Social Security is a uniquely valuable asset, offering:
Viewed through a portfolio‑construction lens, Social Security resembles a risk‑free, inflation‑protected bond—one that private markets cannot replicate at a comparable cost.
2. Plan Under Multiple Scenarios—Not a Single Assumption
A robust plan models Social Security not as a fixed number but as a range. Here’s a simple framework:
This framework will help validate whether spending, gifting, and long‑term capital allocation remain resilient under evolving policy conditions.
3. Delay Benefits When Possible—Even Under Reform Scenarios
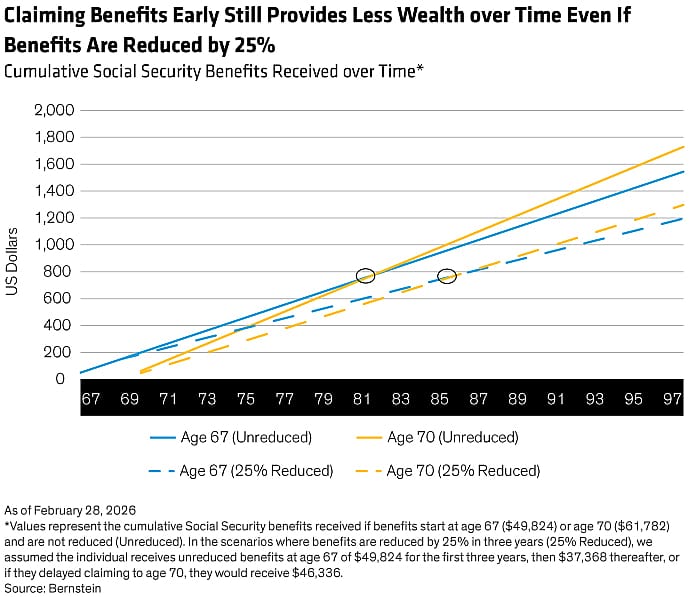
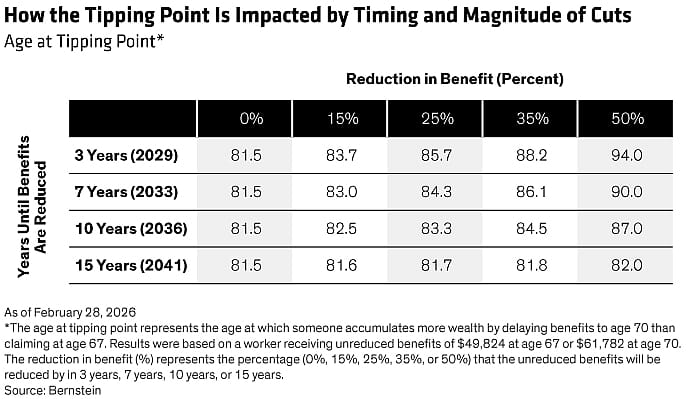
One of the most common questions among high‑earning households is: “If benefits may be cut, shouldn’t I claim earlier?” Surprisingly, the answer is still usually no. In each case, the goal is to find the “tipping points”—the age at which delaying until 70 produces more cumulative wealth than claiming at 67.
Baseline Case (No Benefit Reduction)
A 67‑year‑old eligible for $49,824 per year could instead receive $61,782 per year at age 70. If the retiree chooses to wait until then, the higher annual benefit allows them to break even in 12.5 years. In other words, living beyond age 81.5 favors delaying.
Stress Test: 25% Benefit Reduction at Age 70
Assume the retiree delays to 70—and in the very year they claim, benefits are slashed 25%. Even when the retiree misses out on three full years of benefits and collects reduced benefits of $46,336 per year:
More Drastic, Targeted Cuts
If Congress enacts deeper reductions for certain beneficiaries, such as means‑tested formula changes, the tipping point moves further. For example, a 50% cut in benefits in three years at age 70 pushes the tipping point out to age 94. If the 50% cut is delayed until 2033, the tipping point shifts to age 90 .
Even in these challenging scenarios, delaying preserves better longevity protection, higher inflation‑adjusted income in advanced age and stronger survivor benefits (especially valuable for age‑gap couples).
4. Reevaluate the Tax Treatment of Benefits
For higher‑income households, up to 85% of Social Security benefits are taxable—and the thresholds are not indexed for inflation. What if policymakers raise the taxable percentage or modify how “combined income” is calculated?
In that case, planning opportunities include:
5. Stress Test Lifetime Spending and Legacy Plans
While Social Security uncertainty shouldn’t derail long‑term wealth transfer structures, it should inform your liquidity and spending assumptions. For instance:
While Social Security is likely to change, we don’t see it disappearing as Congress has numerous feasible levers to restore solvency. That means Social Security remains a high-value, inflation-protected asset for affluent families, especially when claiming is delayed to age 70 (even when modeling benefit cuts). Importantly, Social Security planning should be integrated into broader tax, withdrawal, and estate planning.
Ultimately, high‑net‑worth families should:
This story was produced by Bernstein Private Wealth Management and reviewed and distributed by Stacker.


